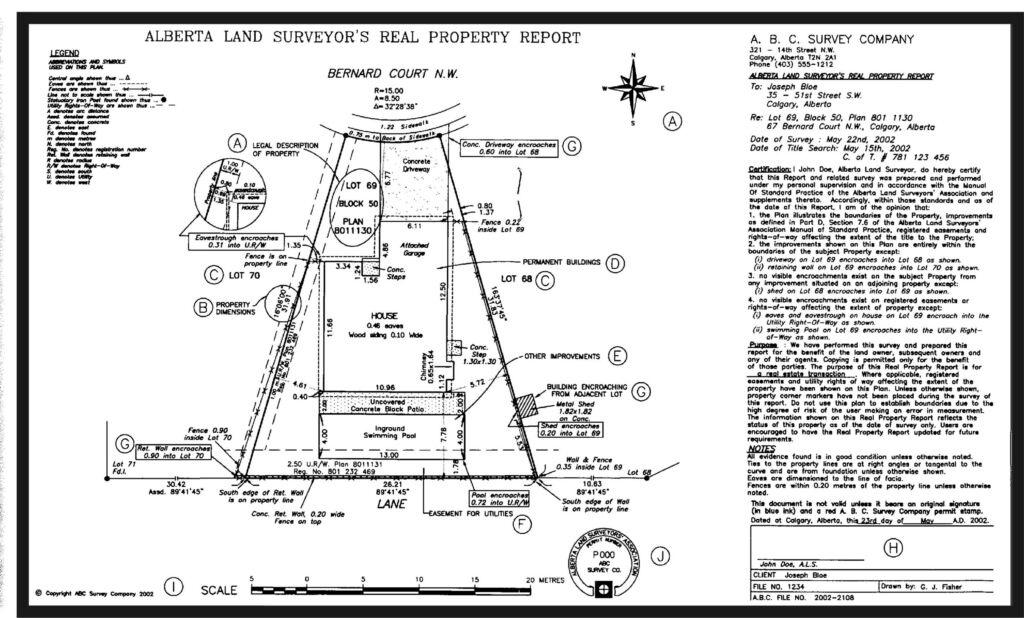
If you’re selling your house, at some point I’m probably going to ask you if you have an RPR, or Real Property Report.
You may have received one when you bought the house, you may have one buried in a file somewhere (look for your legal package your lawyer sent you after closing), or you may have no idea what I’m talking about. All completely normal.
Basically, an RPR is a drawing of your property showing your lot lines and where everything sits: your house, garage, deck, fence, shed, etc.
And here is the important part: please don’t run out and order a new one just because you’re selling your house.
If you already have an RPR, send it to me. Even if it’s old. They are good for 10 years with no changes, sometimes longer.
If nothing has changed since it was done, we may be able to use it. If you’ve since added a fence, deck, shed or something else, then it may no longer be current and we can figure out what makes the most sense from there.
Do you actually need a new RPR?
Maybe. But often, no.
You can have the RPR updated or replaced, but depending on the property that can easily cost $750+.
The other option in many transactions is title insurance, which is usually around $250 and protects the buyer against certain unknown issues with the property or title.
For example, maybe years from now they discover that the fence was accidentally built over the property line, or there is an issue with the location of the deck that nobody knew about when they bought the house. Those are the types of things title insurance can potentially protect against, depending on the policy.
It doesn’t fix the problem or suddenly make an incorrectly placed fence legal. It’s insurance that protects against certain losses if an unknown problem comes up.
So why would anyone get an RPR?
Because sometimes we absolutely should.
If there is something questionable about the property, an unusual lot, a possible encroachment or something else that makes me want to know exactly where everything sits, I may recommend getting one.
But if your house is fully developed, the fence and deck have been there forever, there are no obvious concerns and title insurance will satisfy the requirements of the sale, I’m not automatically going to tell you to spend $750+ on a new RPR.
Honestly, an RPR can be a very expensive piece of paper that you will likely never need again.
In my experience, probably 8 out of 10 transactions use title insurance now. It’s common, it’s considerably less expensive and for a lot of properties it simply makes more sense. And even when there is an RPR, title insurance is still commonly recommended as additional protection. It is that good.
And here’s something I’ve always found interesting: when a lawyer is acting for a buyer, they may want to see a current RPR so they know exactly what the buyer is purchasing. But when that same lawyer is acting for a seller who doesn’t have a current RPR, title insurance is very commonly used to get the transaction closed. That tells you something. Title insurance isn’t some second-rate option we use because we forgot to get an RPR. It’s a legitimate and very common form of protection.
That doesn’t mean RPRs are useless. They definitely aren’t. I just don’t believe in spending my clients’ money unnecessarily.
So if you’re thinking about selling and you find an RPR somewhere in your files, send it to me. And if you can’t find one, don’t panic and definitely don’t order one yet. We’ll figure out whether you actually need it first.
Southwest Edmonton Resource
Get to know me and learn how my extensive local expertise empowers your next purchase or sale.